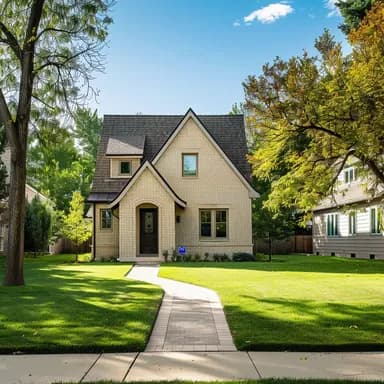
34 Popular House Styles in America: From Colonial to Modern
Popular house styles include Colonial, Craftsman, Ranch, Victorian, Modern, and Contemporary. Each style has distinct architectural features, construction periods, and regional popularity.
The more you know, the more you can save. Browse our deep library of mortgage and home-buying stories. Read about first-time home buyer programs, low- and no-down payment mortgages, refinancing to save money and more.
These are the 10 articles most popular with readers like you this week, based on page views and reader engagement. Join the millions who have trusted Homebuyer.com.
Stats updated November 14, 2026 at 02:56 PM
Popular house styles include Colonial, Craftsman, Ranch, Victorian, Modern, and Contemporary. Each style has distinct architectural features, construction periods, and regional popularity.
18 first-time home buyer programs with low down payments, cash grants, and government assistance.
Homeowners can generate income through renting rooms, Airbnb, home businesses, storage rental, or hosting events. Local regulations may apply.
A letter of explanation (LOE) explains credit issues, employment gaps, or unusual transactions to lenders. Required when underwriters need clarification on your application.
Mortgage rates can be lowered by improving credit scores, buying discount points, shopping multiple lenders, using first-time buyer programs, and choosing shorter loan terms.
Make a strong offer by getting pre-approved, offering 1-3% earnest money, including contingencies, and negotiating based on market conditions and seller motivation.
A mortgage is a loan to buy a home, typically paid over 30 years. The main types are conventional, FHA, VA, and USDA loans, each with different requirements and benefits.
Refinance when rates drop significantly below your current rate, you want to shorten your term, or need cash out. Costs typically 2-5% of loan amount.
The Closing Disclosure is the five-page form with your mortgage's final terms, delivered three business days before closing so you can review every number before you sign.
LLPAs are risk-based fees that adjust mortgage rates based on credit score, down payment, and loan type. Higher risk borrowers pay higher rates through these adjustments.
These articles are increasingly popular with other Homebuyer.com readers over the past week.
Closing costs are fees paid at home purchase closing, typically 2-5% of the loan amount. They include lender fees, title insurance, appraisal, and prepaid items.
Contingency clauses protect buyers by allowing them to back out if certain conditions aren't met. Common contingencies include inspection, financing, appraisal, and home sale contingencies.
Dual agency occurs when one agent represents both buyer and seller. It's legal in most states but creates conflicts of interest. Some buyers prefer separate representation.
PITI is your total monthly payment: Principal, Interest, Taxes, and Insurance. This is what you'll actually pay each month, not just the loan payment.
Seller concessions are closing costs the seller agrees to pay on your behalf, capped at 2 to 9 percent of the price depending on your loan type and down payment.
401k funds can be borrowed to buy a home, or withdrawn (with penalties). Loans must be repaid within 5 years and don't affect credit.
Title companies, attorneys, or brokerages hold earnest money in escrow. Release depends on contingencies in your purchase agreement.
The Federal Reserve sets interest rates that affect mortgage rates. When the Fed raises rates, mortgage rates typically increase. When they lower rates, mortgages get cheaper.
A mortgage gift letter is a signed document from donors stating down payment funds are gifts (not loans). Required by lenders to verify gift funds don't need repayment.
A mortgage rate lock is your lender's promise to hold your interest rate and points for a set number of days while your loan closes, protecting you from rising rates but not lowering your rate if the market falls.
Take a deep-dive into mortgage types. Read about qualifications, approvals, and assistance.
Traditional mortgages with competitive rates
and flexible terms for most buyers
Low down payment option with flexible
credit requirements and government backing
Zero down payment benefits for veterans
and active military service members
Rural home buying program with no
down payment required in eligible areas
Browse our complete collection of mortgage guides, sorted alphabetically and updated regularly.
Data-driven insights to guide your home buying decisions
Join thousands getting today's rates and new programs.
No spam · Unsubscribe anytime
It's good to be a homebuyer. Get today's mortgage rates, new market information, and practical mortgage advice delivered straight to your inbox. It's everything you need.

Use these tools to calculate payments, compare loans, and plan your home buying budget.
Data-driven insights to guide your home buying decisions
It's good to be a homebuyer. Get today's mortgage rates, new market information, and practical mortgage advice delivered straight to your inbox. It's everything you need.

Homebuyer.com is now a part of Opendoor. See the cash offer we'll make for your home.